Ilhan Omar KICKED Out Of Congress! The Squad & Entire Democrats MELTDOWN So Bad It's Hilarious!!...
Ilhan Omar Faces a Fiery House Showdown — The Committee Vote and Financial Questions Behind the Headlines
The political fight surrounding Ilhan Omar became a flashpoint in Washington when House Republicans moved to remove her from the House Foreign Affairs Committee. The decision triggered fierce objections from Democrats and renewed debate over whether congressional discipline was being applied consistently — or wielded as a political weapon.
But one distinction is essential: Omar was removed from a committee, not expelled from Congress. The House voted on February 2, 2023, to remove her from the Foreign Affairs Committee, while she retained her seat representing Minnesota's Fifth Congressional District. The vote became a defining moment in the partisan struggle over congressional oversight, political speech, and the limits of party power.
A Committee Vote Sparks a Partisan Clash
Republicans argued that Omar's previous comments about Israel made her unsuitable to serve on a committee responsible for foreign policy and national security. Democrats countered that the decision was politically motivated and pointed to Republican lawmakers whose own controversial statements had not resulted in comparable consequences.
Omar rejected the move as an attack on her identity and political representation. During the debate, she argued that the decision targeted women of color and highlighted what she described as a double standard in the House.
The dispute quickly expanded beyond the committee assignment itself. Supporters of Omar viewed the vote as an effort to silence a progressive critic of Republican foreign policy. Supporters of the resolution argued that committee assignments carry responsibilities and that lawmakers should be held accountable for their public statements.
The House ultimately approved the resolution. The result was a significant political setback for Omar, but it did not remove her from elected office.
The Financial Questions Behind the Political Battle
Separate financial controversies have also followed Omar for years. In 2019, Minnesota's Campaign Finance and Public Disclosure Board reviewed allegations involving her campaign spending and tax-related expenses.
The board found that certain campaign expenditures were not properly attributable to campaign activity and directed Omar to reimburse her committee approximately $3,469.23. It also imposed a $500 civil penalty. The findings generated additional scrutiny of joint tax returns she had filed with Ahmed Hirsi in 2014 and 2015, before their legal marriage.
Those findings deserve careful description. The state board's review concerned campaign-finance compliance and related documentation; it did not establish that Omar had committed criminal tax fraud. Republican state lawmakers subsequently called for federal and state tax authorities to examine the matter, but a request for an investigation is not proof that the alleged offense occurred.
The distinction is important because political accusations can spread much faster than official findings. Financial records can warrant scrutiny without automatically proving criminal intent or wrongdoing.
Accountability, Political Retaliation, and the Evidence
For Omar's critics, the committee vote and the financial questions fit into a broader argument that elected officials should face scrutiny regardless of party affiliation. They have argued that public office demands transparency and that campaign-finance rules must be enforced consistently.
Democrats, meanwhile, have challenged the motivations behind the committee removal and argued that Republicans were using their majority to punish a prominent political opponent. The Foreign Affairs Committee's Democratic leadership publicly described the vote as an act of political retaliation.
These competing interpretations cannot be resolved simply by declaring one side victorious. The committee vote was an established legislative action. The campaign-finance board's findings were administrative determinations. Broader claims of criminal misconduct require separate evidence and, where applicable, formal findings by the relevant authorities.
What the Episode Actually Reveals
The fight over Omar illustrates how congressional discipline, financial accountability, and partisan conflict can become intertwined. A committee assignment can carry substantial political significance, but losing one is not the same as losing a seat in the House.
Likewise, an official finding that campaign expenses were improperly handled is not interchangeable with a criminal conviction. Responsible scrutiny requires identifying exactly what an investigation established, what remains disputed, and which claims have not been substantiated.
The lasting controversy is therefore larger than a dramatic floor vote. It concerns whether Congress can enforce its standards consistently while ensuring that disciplinary decisions are based on legitimate institutional responsibilities rather than partisan retaliation.
The record offers a clearer picture than the most sensational headlines: Omar lost her Foreign Affairs Committee assignment in 2023, while separate financial questions continued to attract political attention. Those are consequential facts — but they are not evidence that she was expelled from Congress or that every accusation against her was proven.
THEY LIED TO US: The Heartbreaking Secret Cut From Kennedy & Waters' Heated Confrontation!...
John Kennedy’s $47 Million Audit Challenge Raises Questions About Maxine Waters and Federal Spending
A $47 million discrepancy is the kind of figure that demands a clear explanation. When questions arise about federal expenditures, taxpayers have a right to know where the money went, what documentation supports the payments and whether the spending followed the rules established by Congress.
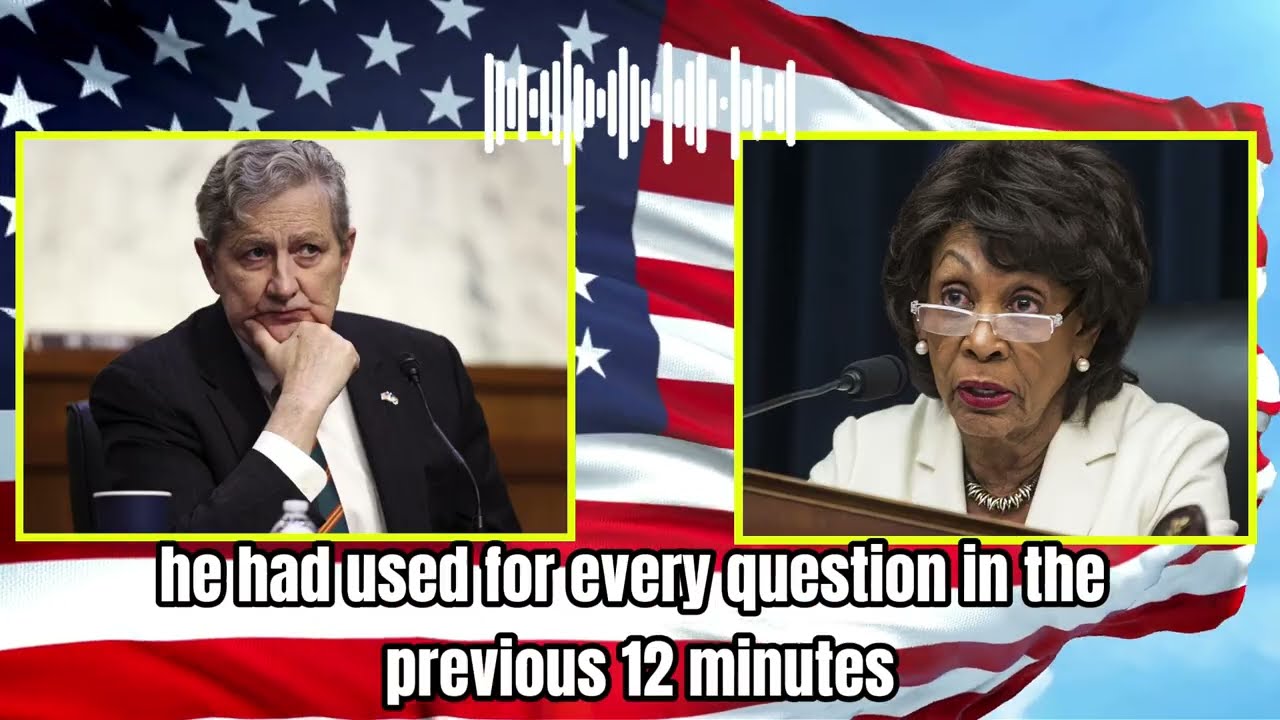
That is the central issue behind a viral account involving Senator John Kennedy and Representative Maxine Waters. The story describes Kennedy comparing a statement allegedly signed by Waters with an audit that reportedly identified millions of dollars in expenditures lacking sufficient supporting documentation.
Although the specific hearing and documents described in the account have not been independently verified, the controversy highlights a broader issue in Washington: the difference between assurances of financial oversight and the records needed to demonstrate that public money was properly accounted for.
The $47 Million Question
The account centers on an alleged federal audit identifying approximately $47 million in expenditures that could not be adequately verified through the available documentation.
Such a finding would raise important questions. Were the payments supported by invoices and financial records? Were the expenditures properly authorized? Did the responsible agency maintain records that allowed auditors to trace the money from approval to final disbursement?
An audit discrepancy does not automatically establish fraud or prove that funds disappeared. In some cases, missing documentation reflects administrative failures, incomplete recordkeeping or difficulties retrieving historical records. In others, it can reveal more serious weaknesses in financial controls.
The distinction matters. Before drawing conclusions about wrongdoing, investigators must establish exactly what the auditors examined and what explanations the responsible officials provided.
Why the Alleged Statement Matters
The viral account describes Kennedy placing two documents side by side: a statement reportedly signed by Waters approximately 14 months earlier and an audit raising questions about millions of dollars in expenditures.
The significance of such a comparison would depend on the exact language of the statement. If it explicitly certified that particular expenditures had been properly documented and independently verified, an audit finding to the contrary could create a serious accountability question.
But a general assurance about oversight is not necessarily the same as a personal certification of every individual payment. The scope of the statement, the programs it covered and the responsibilities of the person signing it would all need to be established.
That is why the original document matters more than a description of it. Its wording would determine whether the alleged contradiction was direct, partial or based on different reporting periods and accounting standards.
The Meaning of an Unverified Audit Entry
Another detail in the account concerns a reference identified as “Line Item 7,” allegedly describing records that could not be verified through standard retrieval procedures.
If authentic, that wording would deserve closer examination. Auditors rely on documentation to confirm that expenditures were legitimate, properly recorded and consistent with applicable requirements. When records cannot be retrieved or verified, the reliability of the financial reporting process can be called into question.
However, an inability to retrieve records through standard procedures does not necessarily mean those records never existed. It may indicate that documents were improperly maintained, archived elsewhere or unavailable during the audit.
The next step would be to determine whether the agency eventually supplied the missing records, whether auditors accepted additional explanations and whether the amount remained unresolved in the final report.
Without those details, the alleged $47 million cannot responsibly be described as stolen, lost or conclusively unauthorized.
Congressional Oversight and the Demand for Documentation
The larger issue is the responsibility of elected officials and federal agencies to demonstrate how public funds are used.
Congressional oversight is not limited to asking whether a program achieved its intended goals. Lawmakers must also examine whether spending was authorized, whether financial controls worked and whether agencies can provide reliable records when auditors request them.
That responsibility applies regardless of party affiliation. A Democratic administration, a Republican administration or an independent agency should face the same basic questions when significant accounting discrepancies arise.
If the alleged findings are confirmed, the appropriate response would be to identify the responsible accounts, obtain the missing documentation, establish whether the expenditures complied with federal requirements and determine whether corrective action is necessary.
The Records Must Provide the Final Answer
The reported confrontation between Kennedy and Waters presents a straightforward question: what documentation supports the millions of dollars identified in the alleged audit?
But answering that question requires the complete audit, the original statement and the relevant financial records—not simply a dramatic comparison of two documents.
May you like
A $47 million discrepancy would be significant enough to warrant a transparent explanation. Yet accountability also requires precision. An unresolved audit finding should be investigated, not automatically treated as proof of misconduct.
Ultimately, public confidence depends on whether government officials can show where taxpayer money went, explain discrepancies and provide the records necessary for independent verification. When those records are incomplete, Congress has a responsibility to keep asking questions until the accounting is clear.